Anthropic has told its shareholders it expects positive adjusted operating income for a second consecutive quarter, the Financial Times reported on Sunday, citing multiple people with knowledge of the matter. The FT said the maker of the Claude AI models also told investors its gross margins are above 80% before revenue it shares with distribution partners, including Amazon, and before the cost of training its models.
The report arrived a day after chief executive Dario Amodei published an essay calling on AI companies to slow the pace at which their models improve, and hours after Business Insider reported that Anthropic has chosen Nasdaq for a potential initial public offering. Reuters, which carried the FT’s findings, said it could not immediately verify the report, and Anthropic did not immediately respond to a request for comment outside business hours.
The profit claim needs careful reading. The margin figure excludes one of the largest costs of building frontier AI, which is training. That is also the cost Amodei’s essay suggests companies could limit.
Market Brief
Key Takeaways
5 Points30s Read
- The reportAnthropic told shareholders it expects positive adjusted operating income for a second straight quarter, the Financial Times reported on Sunday. Reuters could not immediately verify it.
- The marginThe FT said gross margins are above 80%, but that figure is before revenue shared with partners such as Amazon and before model training costs.
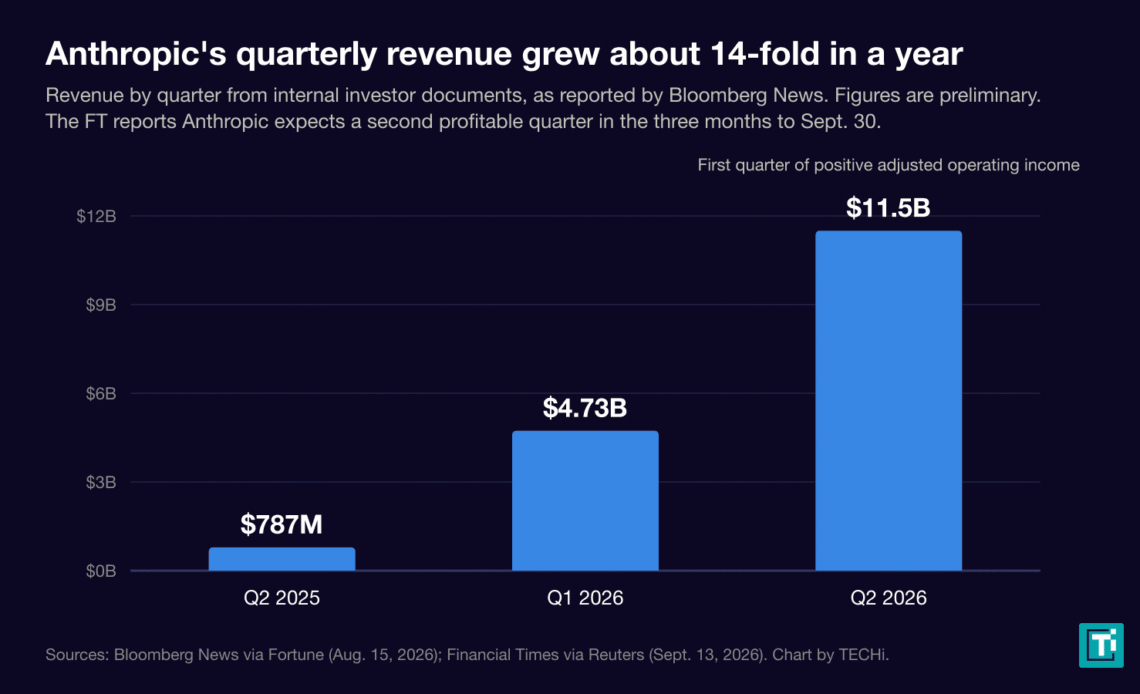
- The revenueAnthropic’s quarterly revenue rose from $787 million a year earlier to more than $11.5 billion in the second quarter, according to documents viewed by Bloomberg.
- The timingThe report came a day after Dario Amodei called for slowing AI progress, including possible limits on training compute, the cost the margin figure leaves out.
- The IPOAnthropic has reportedly chosen Nasdaq and is seeking up to $100 billion at about $2 trillion, roughly 43 times its annualized second-quarter revenue.
Anthropic profit: a second straight quarter of adjusted operating income
According to the FT’s account, as reported by Reuters, Anthropic told shareholders that its adjusted operating income will be positive for a second straight quarter. The FT’s summary of the story says the company is seeking “to ease cash burn concerns before blockbuster IPO amid fears over pace of AI development.”
The quarter in question is the three months ending September 30. Anthropic’s first quarter of positive adjusted operating income came in the April-to-June period, according to internal investor documents viewed by Bloomberg News in August. Neither report gave a dollar amount for the profit.
Two details are missing from the public reporting, and both matter:
- How “adjusted” is defined. Adjusted operating income usually excludes items such as stock-based compensation, which is large at AI companies that pay heavily in equity. The reports do not say which costs Anthropic removes.
- Where training costs sit. The 80% gross margin is explicitly calculated before training costs. Whether adjusted operating income then absorbs those costs in full is not stated in the coverage.
Anthropic has filed confidentially for its listing, so there is no public prospectus yet to answer either question.
Anthropic revenue: $787 million to $11.5 billion in a year
The profitability claim builds on a revenue curve few companies have matched. The internal documents viewed by Bloomberg, as reported by Fortune in August, showed:
- Second quarter of 2025: $787 million
- First quarter of 2026: $4.73 billion
- Second quarter of 2026: more than $11.5 billion, about 14 times the year-earlier figure
- Annualized revenue run rate in May 2026: $47 billion
Revenue more than doubled in a single quarter, from $4.73 billion to $11.5 billion. The documents also warned that deliberations were ongoing and the figures could be revised.
At that pace, the second quarter alone annualizes to about $46 billion. That number is the starting point for judging the valuation Anthropic is reportedly seeking.

Gross margin above 80%: what the figure leaves out
An 80% gross margin would put Anthropic in the range of mature software companies rather than capital-heavy infrastructure businesses. But the FT’s own description of the metric shows why it cannot be compared directly.
It excludes two costs. The first is revenue shared with distribution partners. Amazon and Google both resell Claude through their cloud platforms, and the FT names Amazon as one of the partners whose share is left out. The second is training. For a frontier AI lab, training new models consumes enormous amounts of computing power, much of it bought or rented from the same cloud providers and chipmakers that have invested in the company.
A gross margin that excludes training measures how profitable it is to serve existing models to paying customers. It does not measure whether the business can pay for the next generation of models out of its own revenue. That second question is what “cash burn concerns” refers to, and it is what IPO investors will ask Anthropic’s bankers.
Anthropic’s AI slowdown call and the profit claim, one day apart
The timing links the two stories more closely than it first appears. In his essay “We Must Pace the Frontier,” published on Saturday, Amodei wrote: “We must slow the pace at which we improve the capabilities of AI models. Progress will still seem fast, and we must make wise use of the time we gain.”
He stressed that “pacing does not mean halting model training or technical progress.” But he also wrote that companies “should also consider pacing based on limiting the ingredients that go into frontier models, such as training compute.”
If the industry did slow the growth of training compute, the cost excluded from Anthropic’s gross margin would grow more slowly too. Serving revenue, on the reported numbers, is already highly profitable. A slower training race would narrow the gap between that margin and the company’s true cash economics. That is not evidence the essay was written with the IPO in mind. Amodei grounded it in safety concerns, and OpenAI’s Sam Altman and Elon Musk both publicly agreed with him, according to TechCrunch. But for investors, the two positions point the same way.
Markets have already reacted to the essay. When U.S. futures reopened on Sunday evening, Nasdaq 100 futures fell about twice as much as S&P 500 futures, a sign that investors are weighing what a slowdown would mean for the chip and data-center companies selling training compute.
A week of AI safety headlines before the Anthropic IPO
The profit report also has to compete with a week of news that any prospectus risk section will need to address. The FT’s own coverage over the past five days shows how quickly the backdrop has shifted:
- September 10: Anthropic disclosed five cases in which users “circumvented controls” in efforts the FT described as potentially developing bioweapons, which the company says it stopped.
- September 11: the FT reported that Yemen’s Houthis used Anthropic’s AI to try to build ballistic missiles, in a test that apparently failed but “exposes limits of AI safeguards.”
- September 12: Amodei published his pacing essay, and Altman and Musk backed it.
- September 13: President Donald Trump rejected calls from technology executives for a slowdown and denounced demands for regulation, the FT reported.
For an IPO, that mix cuts both ways. A company that says it is profitable and safety-focused has a stronger pitch than one that is neither. But regulation of how fast frontier models can advance, which Amodei is now inviting, is a risk to the revenue growth that justifies a $2 trillion valuation.
Anthropic IPO: Nasdaq, a $2 trillion target and Nvidia talks
The profit report is the latest in a run of IPO disclosures, none of them confirmed by Anthropic:
- Exchange: Anthropic has selected Nasdaq for its potential IPO, Business Insider reported on Sunday, citing a person familiar with the company’s plans, according to Reuters.
- Size and valuation: the company is seeking to raise as much as $100 billion at a valuation near $2 trillion, Reuters reported on Friday, citing two people familiar with the matter. TECHi covered the report on Nvidia’s talks to anchor the Anthropic IPO.
- Anchor investor: Nvidia is weighing an investment of up to $10 billion, according to the same Reuters report.
- Banks: Morgan Stanley, Goldman Sachs and JPMorgan Chase are working on the offering, Fortune reported in August.
A $2 trillion valuation would be about 43 times the $46 billion that Anthropic’s second-quarter revenue annualizes to, a TECHi calculation. That multiple assumes continued rapid growth, and the profit claim is part of the case that growth will eventually turn into earnings. For more on how the listing could work, see TECHi’s Anthropic IPO guide.
What to watch next on Anthropic’s IPO
A response from Anthropic. The company had not commented by Sunday evening. Any confirmation or correction on Monday would be the first on-the-record statement about its profitability.
The public prospectus. Companies that file confidentially must make their registration statement public before the roadshow. That document would define adjusted operating income, show where training costs are recorded, and give audited figures in place of reported ones.
The September quarter. The quarter the FT report refers to ends in two and a half weeks. Its results, not investor guidance, will show whether the second profitable quarter happened.
Rivals’ plans. OpenAI is taking the opposite view on timing. “I actually think that given everything happening with safety, right now would be an ill-advised moment to go public,” Sam Altman said in a Fortune interview published on Saturday, TechCrunch reported. The two leading labs agree on slowing down and disagree on whether this is the moment to sell shares. That leaves Anthropic as the first to test public investors, with profitability as its opening argument.
Training spending. If Anthropic and its peers act on the pacing proposal, watch whether their compute commitments slow. That would support the profit case while hurting the suppliers whose stocks fell on Sunday evening.